Getting an EIN With No SSN and No ITIN
The company is formed. The bank wants an EIN. The application asks for the responsible party's Social Security number, and you do not have one.
Most people stop here, because the form reads as though it has no answer for them. It has one, and the IRS prints it in the instructions to the form itself.
On Form SS-4, line 7b, the IRS instructs: "Enter “foreign” or N/A on line 7b if the responsible party doesn’t have and is ineligible to obtain an SSN or ITIN. An entry is required."
That is the blockage on the form itself, and it is one word in a box. The rest of this page is the route that word sits on, and one wall further down the road.
The IRS route in one table
Every cell is taken from the IRS's own instructions for Form SS-4 or its EIN page, with the source under the table.
| What the IRS publishes | |
|---|---|
| Line 7b of Form SS-4 | Enter “foreign” or N/A if the responsible party does not have and is ineligible to obtain an SSN or ITIN. An entry is required1 |
| The online application | Not available with no legal residence, principal place of business, or principal office or agency in the United States or U.S. territories2 |
| The online application also needs | A valid SSN, EIN or ITIN for the principal officer, general partner, grantor, owner, trustor, etc.3 |
| By phone, with no residence, place of business or office in the U.S. or its territories | 267-941-1099, not a toll-free number, 6:00 a.m. to 11:00 p.m. Eastern time, Monday through Friday4 |
| The caller must be | Authorized to receive the EIN and answer questions concerning Form SS-45 |
| By fax, with no residence or office in a state or D.C. | 855-215-1627 if within the United States, 304-707-9471 if outside the United States6 |
| By fax, the EIN arrives | Generally within 4 business days, under the Fax-TIN program7 |
| For the fax reply | Provide your fax number so the IRS can fax the EIN back to you8 |
| By mail, the EIN arrives | In approximately 4 weeks9 |
| How many per day | 1 EIN per day, whether online or by phone, mail or fax10 |
Every figure above, and where it was published:
If you have neither number and cannot get one, one word in one box gets you past line 7b, and the IRS prints it in the instructions to its own form.
Book Your Assessment CallLine 7b, and the word that goes in it
The IRS states the general rule first, and it is the rule that makes people think the door is shut. "Unless the applicant is a government entity, the responsible party must be an individual (that is, a natural person), not an entity."
The responsible party is defined rather than left open. The IRS calls it "the person who ultimately owns or controls the entity or who exercises ultimate effective control over the entity." For a single-member LLC that is ordinarily its owner.
Then the exception, in the same instructions, for the case where that person has neither number and cannot get one. An entry is required, and the entry is “foreign” or N/A.
Note the condition the IRS attaches: does not have, and is ineligible to obtain. Those are two tests in one sentence, not one.
The online application is closed to you, and the IRS says so
This is the part that wastes the most time, because the online tool does not explain itself when it fails. The IRS does.
"If you have NO legal residence, principal place of business, or principal office or agency in the United States or U.S. territories, you can’t use the online application to obtain an EIN. Please use one of the other methods to apply."
The other methods are published on the same pages. The IRS gives a telephone route under a heading that reads, in its own words, that the option is available to international applicants only: "you may call 267-941-1099 (not a toll-free number), 6:00 a.m. to 11:00 p.m. (Eastern time), Monday through Friday, to obtain an EIN."
For the form itself the IRS publishes "Fax 855-215-1627 (within the U.S.) or 304-707-9471 (outside the U.S.)" and a mailing address, Internal Revenue Service, Attn: EIN International Operation, Cincinnati, OH 45999.
One limit applies across all of them at once: "You can apply only for 1 EIN per day, whether online or by phone, mail or fax."
How long it takes, in the IRS's own words. Under the Fax-TIN program, the instructions say, "you can receive your EIN by fax generally within 4 business days", if you give your fax number for the reply, and by post: "You will receive your EIN in the mail in approximately 4 weeks." Those are the only two turnaround figures on this page. Any other number in circulation has no source behind it here.
A disregarded LLC does not always need its own EIN
Worth checking before spending a week on it, because the IRS draws the line around use rather than around existence.
"A single-member LLC that is a disregarded entity that does not have employees and does not have an excise tax liability does not need an EIN. It should use the name and TIN of the single member owner for federal tax purposes."
And then the sentence that covers almost everyone who arrives at this page: "However, if a single-member LLC, whose taxable income and loss will be reported by the single member owner needs an EIN to open a bank account or if state tax law requires the single-member LLC to have a federal EIN, then the LLC can apply for and obtain an EIN."
So the bank is a published reason, not a workaround. That is a useful thing to know when a form asks why you are applying.
The EIN is where the reporting obligations start, not where the paperwork ends.
Book Your Assessment CallThe S corporation election is not available to a non-resident
This sits one step past the EIN, and it is the reason this page carries a section that looks off-topic. A great deal of advice tells non-resident LLC owners to elect S corporation treatment. The IRS publishes that they cannot.
On its S corporations page, listing who may hold shares, the IRS states that a corporation "May not be partnerships, corporations or non-resident alien shareholders".
The instructions to Form 2553 put the same test on the form itself: "It has no nonresident alien shareholders (other than as potential current beneficiaries of an ESBT)."
Two separate IRS publications, the same bar. The classification election that is open is a different form: Form 8832, and the IRS states its timing plainly, that an election "cannot take effect more than 75 days prior to the date the election is filed, nor can it take effect later than 12 months after the date the election is filed."
Whether either is a good idea for a particular company is a question for the call, and this page reaches no conclusion about it.
The obligation with a deadline on it
One thing changes hands quietly. If the responsible party changes, the IRS attaches a clock to telling them: "Use Form 8822-B, Change of Address or Responsible Party – Business PDF to report changes to your responsible party, address or location to the IRS within 60 days."
And the EIN is where a second obligation begins rather than ends. The SS-4 instructions name it directly, that a disregarded entity uses its EIN "where a U.S. disregarded entity is wholly owned by a foreign person, to file information returns on Form 5472". What that filing is, and what missing it costs, is a page of its own.
What this page does not do
It does not tell you whether you are ineligible for an SSN or an ITIN. That is a determination about a person, and the IRS instruction sets two conditions rather than one.
It gives no processing time beyond the two IRS figures quoted above, and it says nothing about anyone applying on your behalf.
It recommends no classification and computes no tax. Every quotation above is the IRS in its own words, each read on the date shown under Sources, and each of those pages carries its own review date that will move.
If you have neither number and cannot get one, one word in one box gets you past line 7b, and the IRS prints it in the instructions to its own form.
Book Your Assessment CallWhat the work looks like
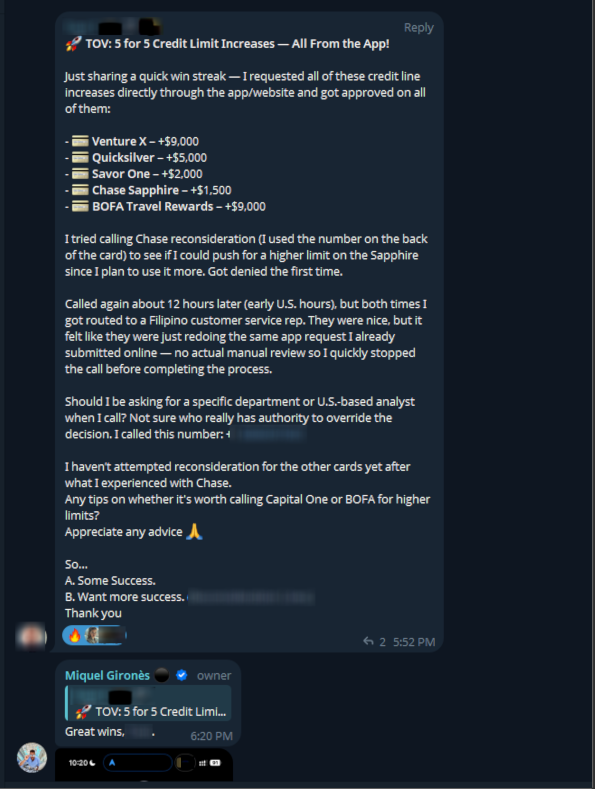
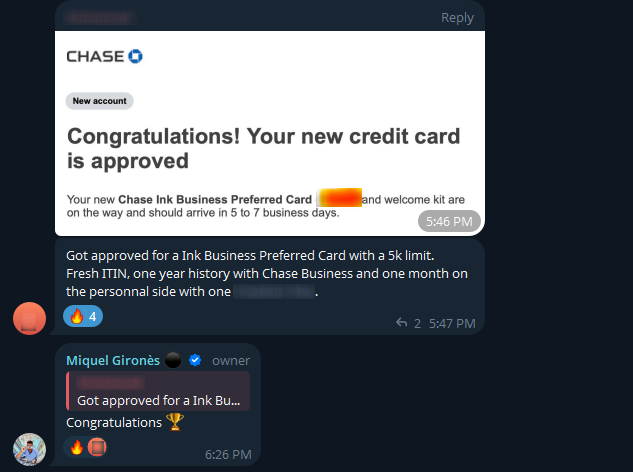



Real client wins, straight from the Hall of Wins.
The US company series
The rest of the picture
- Find your routeTell it what you are trying to do and it maps the guides to read in order.
- ITIN document checklistPick your situation, get the exact list the IRS accepts.
- What it costsPublished prices and timelines, service by service.
- US credit calculatorWhat your spend returns at the rates issuers publish today.
FAQ
Can I get an EIN without an SSN or an ITIN?
Why does the online EIN application not work for me?
How do I apply from outside the United States?
How long does an EIN take this way?
Does my single-member LLC actually need its own EIN?
Can a non-resident elect S corporation treatment for an LLC?
Sources
The published pages this guide draws on, each read on the date shown.
The order these steps actually go in
The assessment call covers where the company sits, which number you need before which step, and what the structure you are considering carries with it. Free, qualified, and direct about what applies to you.
Book Your Assessment CallThis guide reports what the authorities and institutions involved publish, quoted, with the date each source was read. It is not tax, legal or immigration advice. Published rules change, and an individual case can turn on facts no page can see.

Founder & CEO, The First Class Citizen